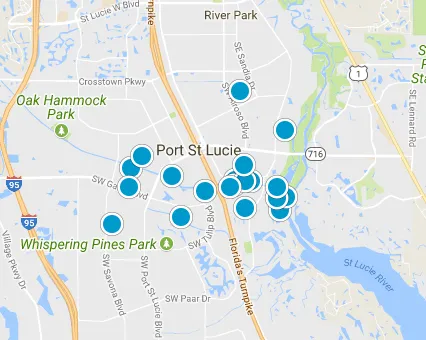
Search 34983 Homes Under $200,000 With No HOA
34983 Homes Under $200,000 With No HOA

Handyman's dream in Port St Lucie! This 3 bed / 2 bath frame home offers 1,273 SF of living space on a fenced .23-acre lot — solid bones with great potential for the righ...
- 3 Beds
- 2 Baths
- B26064562 MLS
- 34983 Zip Code
- Port St Lucie Section 43 SubDv.

Located at the signalized intersection of SE Walters Terrace and SE Floresta Drive, this 0.23-acre (10,000 SF) residential parcel offers an excellent opportunity in one o...
- B26054335 MLS
- 34983 Zip Code
- Port St Lucie Section 3 SubDv.

Located at the signalized intersection of SE Walters Terrace and SE Floresta Drive, this 0.26-acre (11,250 SF) residential parcel offers an excellent opportunity in one o...
- B26054344 MLS
- 34983 Zip Code
- Port St Lucie Section 3 SubDv.

Located at the signalized intersection of SE Walters Terrace and SE Floresta Drive, this 0.23-acre (10,000 SF) residential parcel offers an excellent opportunity in one o...
- B26054330 MLS
- 34983 Zip Code
- Port St Lucie Section 3 SubDv.

BEAUTIFUL OVERSIZED BUILDING LOT WITH 160 FEET OF FRONTAGE ON PAVED ROAD WITH NO HOA FOR LARGER HOMES IN THE HEART OF PORT SAINT LUCIE ON THE BORDER OF PORT SAINT LUCIE ...
- B26083525 MLS
- 34983 Zip Code
- Port St Lucie Section 48 1st Replat SubDv.

None
- 3 Beds
- 2 Baths
- R11132049 MLS
- 34983 Zip Code
- Port St Lucie Section 45 SubDv.

This prime lot in Port St. Lucie, Florida, is now available for your new Florida home. Conveniently located just minutes away from shopping, dining, and other essential a...
- R11014902 MLS
- 34983 Zip Code
- Port St Lucie Section 27 SubDv.

Buy now, build later! Whether building your dream home or perhaps an investment property, this .33 AC oversized corner lot checks all the boxes. No HOA, public utilities ...
- B26080893 MLS
- 34983 Zip Code
- Port St Lucie Section 25 SubDv.

PRIME RIVER PARK LOCATION! Ready-to-build 10,000 sq ft residential parcel in the heart of River Park. Unbeatable location offering quick, direct access to I-95 and major ...
- B26086018 MLS
- Northport Village Bldg.
- 34983 Zip Code
- Port St Lucie Section 27 SubDv.

Discover a prime, build-ready vacant lot in Port St. Lucie — a level, cleared parcel that offers an ideal canvas for your custom single-family home. The lot has been surv...
- A12087819 MLS
- 34983 Zip Code
- Port St Lucie Section 27 SubDv.

Now available! Port Saint Lucie residential lot for your new Florida home. Conveniently located minutes from shopping and dining establishments. Please note that owners w...
- R11015046 MLS
- 34983 Zip Code
- Port St Lucie Section 27 SubDv.

Huge residential lot that can accommodate a large home with room for a pool. In a quiet community. Directly across the street from a neighborhood park with a pond. Close ...
- B26070225 MLS
- 34983 Zip Code
- Port St Lucie Section 13 SubDv.

Build your future in an established Port St. Lucie neighborhood with this residential lot on SE Proctor Ln. Conveniently located near US-1, shopping, dining, parks, schoo...
- M20056623 MLS
- Port St Lucie Sec 03 Bldg.
- 34983 Zip Code
- Port St Lucie Sec 03 SubDv.

PRIME PORT ST. LUCIE LOT! Ready to Build your Dream Home? This Excellently Located, High and Dry Vacant Lot is already Partially Cleared and Offers Unbeatable PRIVACY. En...
- B26047574 MLS
- 34983 Zip Code
- Port St Lucie Section 28 SubDv.

Your Florida dream starts here! This cleared, ready to build 10,000 sq ft lot in Port St. Lucie is primed for your custom home; bring your own builder and design exactly ...
- B26075682 MLS
- 34983 Zip Code
- Port St Lucie Section 4 SubDv.

The property features a generous depth and ample room for a thoughtfully designed home, outdoor living space, pool, and tropical landscaping. An already cleared lot surro...
- B26073374 MLS
- 34983 Zip Code
- Port St Lucie Section 25 SubDv.

LOOKING FOR AN ESTABLISHED NEIGHBORHOOD TO BUILD ON ? DO NOT MISS THIS. NO BACKYARD NEIGHBORS FOR EXTRA PRIVACY
- B26066327 MLS
- 34983 Zip Code
- Port St Lucie Section 48 1st Replat SubDv.

Great location. Great neighborhood. No through traffic. Only about two dozen homes on this street.
- B26066343 MLS
- 34983 Zip Code
- Port St Lucie Section 43 SubDv.

This vacant land presents a unique opportunity for discerning buyers looking to invest in real estate in Port St. Lucie, Florida. With its ideal location, this parcel is ...
- B26089239 MLS
- 34983 Zip Code
- Port St Lucie Section 43 SubDv.

Discover the perfect opportunity to build your dream home on this spacious 0.23-acre vacant lot in the heart of Port St. Lucie. Nestled in a peaceful, desirable no HOA ne...
- B26054204 MLS
- 34983 Zip Code
- Port St Lucie Section 10 SubDv.

Cleared lot.
- B26044922 MLS
- 34983 Zip Code
- Port St Lucie Section 27 SubDv.

MAKE YOUR DREAMS HOUSE!SEND THE OFFER!
- R11138361 MLS
- 34983 Zip Code
- Port St Lucie Section 4 SubDv.

Discover the opportunity to bring your dream home to life at 590 SW Carter Avenue in Port St. Lucie! Situated on an approximately 10,000-square-foot residential lot , thi...
- B26092132 MLS
- Port St Lucie Bldg.
- 34983 Zip Code
- Port St Lucie SubDv.

BUILD YOUR DREAM HOME IN PORT ST. LUCIE! Great opportunity to build a single-family home on this beautifully maintained and landscaped lot at 673 SE Damask Avenue. The pr...
- B26065194 MLS
- 34983 Zip Code
- Port St Lucie Section 10 SubDv.

Build your dream home or invest in one of Port St. Lucie's fastest-growing communities! This 10,000-square-foot vacant residential lot is located in an established neighb...
- B26050007 MLS
- 34983 Zip Code
- Port St Lucie Section 25 SubDv.

Vacant Land Opportunity in Port St. Lucie 325 NW Primavista Blvd, Port St. Lucie, FL 34983 Prime vacant lot located in the highly desirable St. Lucie West area! This pro...
- B26025775 MLS
- 34983 Zip Code
- Port St Lucie Section 27 SubDv.

Location is everything! Just minutes away from excellent local schools (including Northport K-8 and Southern Oaks Middle School), shopping, dining, and outdoor recreation...
- B26070543 MLS
- 34983 Zip Code
- Port St Lucie Section 26 SubDv.

MAP QUEST
- A11883807 MLS
- 34983 Zip Code
- Port St Lucie Section 2 SubDv.
34983 Homes Under $200,000 With No HOA
This is close to the lowest entry point into central Port St. Lucie: an established part of the city, no homeowners association, and a price under $200,000. Inventory is thin and it goes quickly, so this page is as much about knowing what to do when something appears as it is about browsing. The listings above are 34983 homes under $200,000 with no HOA.
- Homes for Sale
- What to Expect
- The Question That Decides Everything
- How to Buy at This Price Safely
- If Nothing Is Showing
- Other Searches
- FAQs
What to Expect at This Price in 34983
34983 is central Port St. Lucie — east of I-95, around Port St. Lucie Boulevard, out toward the hospital and US-1. It built out earlier than the western sections, so the housing here is older, and under $200,000 you are at the older end of that.
Realistically: smaller two or three-bedroom homes, often one bath or one-and-a-half, generally on the original quarter-acre lots. Some will be well-maintained homes owned a long time by the same family. Others will be estate sales, foreclosures or investor flips. A few will be attached villas, though those usually come with the association this search is meant to avoid.
What you get for the price that you would not get elsewhere in South Florida: a full lot, mature trees, no dues, and a central location. What you generally do not get: square footage, updated systems, or a house that needs nothing.
The Question That Decides Everything: Can You Insure It?
At this price, on housing of this age, insurability is the single factor that decides whether a deal happens. It outranks the kitchen, the yard and the price itself, because a home you cannot insure is a home you cannot finance.
| Roof age and material | The first thing an insurer asks. Many carriers will not write or renew past a certain age on shingle. Get the age before you view, not after you offer. |
|---|---|
| Electrical panel | Several older panel brands are effectively uninsurable and have to be replaced before a policy will issue. Common on housing of this vintage. |
| Plumbing material | Polybutylene and deteriorated cast iron both prompt carrier questions and can mean a repipe. |
| Four-point inspection | On older homes insurers require one covering roof, electrical, plumbing and HVAC. It is a short report and it is what your quote is built on. |
| Wind mitigation | Documents construction type and opening protection. Inexpensive, and it is what earns you the credits that make the premium affordable. |
How to Buy at This Price Safely
- Be fully underwritten, not just pre-qualified. At this price you are competing with cash investors. Being underwritten is the closest a financed buyer gets to competing on equal terms.
- Know your loan type before you look. FHA and VA appraisers apply minimum property standards, and an as-is seller may decline the repairs. Conventional or a renovation loan is frequently the better route on a house that needs work.
- Budget the repairs honestly. Price the roof, the panel and the air conditioning as real numbers, not optimism. The purchase price is not the cost of the house.
- Check permits on additions. Enclosed garages and added rooms are common here and often unpermitted, which affects the appraisal, the insurance and your eventual resale.
- Consider a renovation loan. It funds the purchase and the work together, which at this price is frequently the difference between a house that works and one you cannot afford to fix.
If Nothing Is Showing in This Search
That is the market, not a broken filter. Supply under $200,000 anywhere in Port St. Lucie is genuinely tight and has been for some time. Three sensible responses: widen to $200,000 to $250,000, where the market opens up considerably; look at foreclosures, which trade below market for a reason but are real opportunities if you can handle as-is; or get on an alert so you hear the day something lists. At this price, speed is most of the strategy.
Want to move fast when one appears?
At this price the buyer who is already underwritten wins. I can get you there, and tell you in a phone call whether a specific house is insurable.
RE/MAX — Port St. Lucie agent.
Other Searches
- All 34983 Homes
- 34983 Pool Homes
- PSL $200K–$250K
- CBS $150K–$200K
- Foreclosures Under $150K
- No HOA $250K–$300K
- All Port St. Lucie Homes
Frequently Asked Questions
Can you buy a house in 34983 under $200,000?
Sometimes, but inventory is tight and it moves fast. What appears tends to be smaller older homes on the original quarter-acre lots, estate sales, foreclosures and investor flips. The listings on this page are filtered to exactly that search and update as the MLS updates.
Do these homes have an HOA?
This search is filtered to homes with no association, and most of 34983 has none anyway — it was platted as individual lots rather than as master-planned communities. That means no dues, and no dues counted against you when a lender works out what you qualify for.
Why does insurance matter so much at this price?
Because a home you cannot insure is a home you cannot finance, and older housing stock is exactly where Florida carriers decline to quote. Roof age is the main trigger, followed by the electrical panel and plumbing material. Get a quote during your inspection period — it is the most common reason contracts in this band collapse.
What is a four-point inspection?
A short report covering roof, electrical, plumbing and HVAC that Florida insurers require on older homes before they will write a policy. It is separate from your home inspection and it is what your premium is calculated from.
Can I use FHA or VA financing on a home in this range?
Often, but condition rather than price is the constraint. Both apply minimum property standards, so an end-of-life roof or active leaks can trigger required repairs that an as-is seller will not make. Conventional financing or a renovation loan is frequently the more practical route here.
What is a renovation loan and would it help me here?
It lets you finance the purchase and the repairs in a single mortgage, rather than needing cash for the work on top of your down payment. At this price, where most of what is available needs something, it is often what makes the difference between a house that works and one you cannot afford to fix. I can walk you through whether you qualify.
How do I compete with cash investors?
By being fully underwritten rather than pre-qualified, by being able to view and offer quickly, and by keeping your contingency periods tight but realistic. You will not out-price a cash buyer, but you can out-prepare one — and many sellers prefer a clean financed offer to a low cash one.
Address Search
Homes for Sale by Zip Code Port Saint Lucie
Interactive Map Search