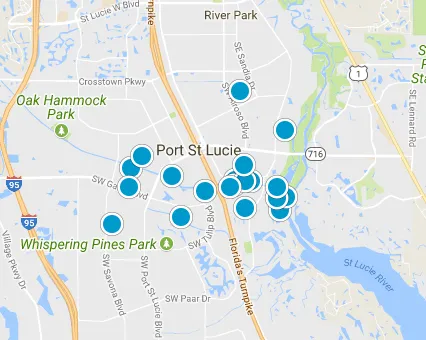
Search Homes for Sale in Port St. Lucie
Homes for Sale in Port St. Lucie

Bring your vision to this lakefront home in Kings Isle! Located in the Isle of San Marino section of this desirable 55+ gated St. Lucie West community, this 2-bedroom, 2-...
- 2 Beds
- 2 Baths
- B26063971 MLS
- St Luice West Plat #62 Bldg.
- 34986 Zip Code
- St Lucie West Plat No 36 SubDv.

Handyman's dream in Port St Lucie! This 3 bed / 2 bath frame home offers 1,273 SF of living space on a fenced .23-acre lot — solid bones with great potential for the righ...
- 3 Beds
- 2 Baths
- B26064562 MLS
- 34983 Zip Code
- Port St Lucie Section 43 SubDv.

The ultimate nature lovers dream home backed up to a preserve filled with birds that frequently visit. Enjoy the Florida resort golfing lifestyle a worry free Islander II...
- 2 Beds
- 2 Baths
- B26021832 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- Eagle's Retreat At Savanna Club Phase 2 SubDv.

Designer-grade 2-bedroom, 2-bathroom, 1-car-garage CBS home built in 2021, located in Spanish Lakes Land Development. The oversized designer driveway leads through the ga...
- 2 Beds
- 2 Baths
- B26083793 MLS
- Spanish Lakes Bldg.
- 34952 Zip Code
- Spanish Lakes One Leasehold Estates SubDv.

Waterfront living in the active 55+ community of Spanish Lakes One! This 2-bedroom, 2-bath home is situated on a desirable lakefront lot and offers an open, light-filled ...
- 2 Beds
- 2 Baths
- B26079488 MLS
- 34952 Zip Code
- Spanish Lakes One Leasehold Estates SubDv.

Here is a great investment opportunity with tons of potential! This home is ready for a new owner to bring their vision and personal touches to life. While it could use s...
- 3 Beds
- 2 Baths
- B26068106 MLS
- 34952 Zip Code
- River Park Unit 3 SubDv.

Experience easy Florida living in this beautifully maintained 2-bedroom, 2-bath home nestled in the desirable 55+ community of Spanish Lakes One. This inviting residence ...
- 2 Beds
- 2 Baths
- B26056029 MLS
- 34952 Zip Code
- Spanish Lakes One Leasehold Estates SubDv.

Welcome to this charming single-story residence in Kings Isle Phase 1, Port St. Lucie, offering waterfront living in a well-established community. This 1,233-square-foot ...
- 2 Beds
- 2 Baths
- B26043378 MLS
- 34986 Zip Code
- Kings Isle Phase 1 SubDv.

Florida living at its finest in this fully updated Presidents Choice model located in the desirable Savanna Club 55+ community. This spacious 3-BR, 2BA split floor plan o...
- 3 Beds
- 2 Baths
- B26046897 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- Eagle's Retreat At Savanna Club Phase 2 SubDv.

Immaculate 2021 CBS Spanish Lakes single family home with full impact glass and metal roof! Furniture & Furnishings fully negotiable so you could move right in to your ne...
- 2 Beds
- 2 Baths
- M20056310 MLS
- Spanish Lakes One Leasehold Estates Bldg.
- 34952 Zip Code
- Spanish Lakes One Leasehold Estates SubDv.

Premium upgrades and move-in ready, this CBS home delivers style and value! Interior features ceramic wood-plank flooring throughout (including lanai), plantation shutter...
- 3 Beds
- 2 Baths
- B26002794 MLS
- 34952 Zip Code
- Spanish Lakes 1 SubDv.

Welcome home to this lakefront Pelican model in the Savanna Club 55+ community. Home offers 3 bedrooms, 2 baths + a den/office and an oversized 2 car garage, with a 35 f...
- 3 Beds
- 2 Baths
- R11157647 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- Eagle Retreat At Savanna Club SubDv.

Seller is open to renting this home furnished. Discover over 1,800 sq. ft. of comfortable living in this beautifully maintained Crane Model on a desirable golf course/pre...
- 2 Beds
- 2 Baths
- R11128126 MLS
- 34952 Zip Code
- The Links At Savanna Club SubDv.

CBS RETREAT! This 3BR/2BA home offers resort living at an unbeatable value. Built for peace of mind, the residence features a durable METAL ROOF, IMPACT WINDOWS and PLANT...
- 3 Beds
- 2 Baths
- R11159056 MLS
- Spanish Lakes Bldg.
- 34952 Zip Code
- Spanish Lakes One Leasehold Estates SubDv.

Welcome to this charming 2-bedroom, 2-bathroom manufactured home located in Spanish Lakes One Leasehold Estates in Port St. Lucie. Offering 1,451 square feet of comfortab...
- 2 Beds
- 2 Baths
- B26052199 MLS
- 34952 Zip Code
- Spanish Lakes One Leasehold Estates SubDv.

Roof 2006, Hot water heater 2021, A/C 2015....Charming 2-bedroom, 2-bath home in Port St. Lucie! This property features a bright, functional layout with spacious living ...
- 2 Beds
- 2 Baths
- B26014014 MLS
- 34952 Zip Code
- Port Saint Lucie SubDv.

Property is a great fixer upper opportunity to buy and hold or fix and flip. Has great bones and great upside.
- 4 Beds
- 2 Baths
- B26044863 MLS
- 34953 Zip Code
- Port St Lucie Section 17 SubDv.

Opportunity in Port St. Lucie! This single-story home offers 2 bedrooms, 2 bathrooms, an attached garage, and a 10,000-square-foot lot. With 912 square feet of living are...
- 2 Beds
- 2 Baths
- A12096240 MLS
- 34953 Zip Code
- Port St Lucie Section 19 SubDv.

Short sale. Partially approved - price is the appraised value. Wood frame home that needs renovation. This 3-bedroom, 2-bath pool home has no HOA and is ready for it's ne...
- 3 Beds
- 2 Baths
- F10485054 MLS
- 34984 Zip Code
- Port St Lucie Sec 13 SubDv.

This charming Cottage floorplan blends cozy comfort with spacious versatility, featuring a large open concept layout, 1 bedroom plus a bedroom sized den, and 1.5 baths, t...
- 1 Beds
- 2 Baths
- R11120816 MLS
- Spanish Lakes One Bldg.
- 34952 Zip Code
- Spanish Lakes One SubDv.

A welcoming layout and generous outdoor space define this 2-bedroom, 2-bath home with an attached 1-car garage. The property features a covered front porch, rear patio, a...
- 2 Beds
- 2 Baths
- F10548841 MLS
- 34983 Zip Code
- Port St Lucie Sec 26 SubDv.

Short Sale Approved Opportunity in Port St. Lucie. Great value for buyers. This property features a spacious layout, comfortable living areas, and abundant natural light....
- 2 Beds
- 2 Baths
- B26024449 MLS
- 34953 Zip Code
- Port St Lucie Section 11 SubDv.

INVESTOR SPECIAL OR PERFECT OPPORTUNITY TO BUILD SWEAT EQUITY! This 3 bedroom, 2 bath home offers 1,225 square feet of living space and sits on an oversized 0.33 acre cor...
- 3 Beds
- 2 Baths
- B26092685 MLS
- 34983 Zip Code
- Port St Lucie SubDv.

Opportunity awaits in this 3-bedroom, 2-bath home located in the heart of Port St. Lucie! Situated on a generously sized lot, this property offers a large backyard with p...
- 3 Beds
- 2 Baths
- B26010740 MLS
- 34984 Zip Code
- Port St Lucie Section 18 SubDv.

Beautiful Savanna Club
- 2 Beds
- 2 Baths
- B26077983 MLS
- 34952 Zip Code
- Fairways At Savanna Club Replat No 1 SubDv.

INVESTOR SPECIAL! Opportunity awaits in Port St. Lucie! This 3-bedroom, 2-bath home features a 2023 roof and offers a great opportunity for investors, renovators, or buye...
- 3 Beds
- 2 Baths
- B26084780 MLS
- 34984 Zip Code
- Port St Lucie Section 18 SubDv.

Welcome to 322 NW Tuscany in the desirable 55+ gated community of Kings Isle in St. Lucie West! This well-maintained 2-bedroom, 2-bath, 2-car garage home offers 1,372 sq....
- 2 Beds
- 2 Baths
- B26067131 MLS
- 34986 Zip Code
- Kings Isle Phase 1 SubDv.

Welcome to 527 NW Portofino Lane, a charming home tucked within the gated Kings Isle community in the heart of St. Lucie West. Offering two bedrooms, two bathrooms, appro...
- 2 Beds
- 2 Baths
- B26082982 MLS
- Kings Isle Bldg.
- 34986 Zip Code
- Kings Isle SubDv.

Experience comfort, style and unmatched value in the La Casita Floor Plan—featuring a spacious open-concept layout, 1 car garage, two bedrooms, two baths, a spacious walk...
- 2 Beds
- 2 Baths
- B26068238 MLS
- 34952 Zip Code
- Spanish Lakes Riverfront SubDv.

Come live the Florida lifestyle in this manufactured home community with resort style amenities including an 18-hole golf course, three swimming pools, three recreation ...
- 2 Beds
- 2 Baths
- B26070432 MLS
- 34952 Zip Code
- Savanna Club Plat Phase Three SubDv.

Experience comfort, style and unmatched value in the La Casita Floor Plan—featuring a spacious open-concept layout, 1 car garage, two bedrooms, two baths, a spacious walk...
- 2 Beds
- 2 Baths
- B26071668 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.

LAND OWNED, SAVE YOU THOUSAND A YEAR ON LAND LEASE! Rare 3-bedroom, 2-bath manufactured home in Savanna Club on corner lot offers 1,664 square feet of single-story livin...
- 3 Beds
- 2 Baths
- B26073041 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- Savanna Club Plat I SubDv.

Welcome to Kings Isle in Port St. Lucie, a sought-after 55+ resort-style community. This well-maintained 2-bedroom, 2-bath CBS home offers 1,430 sq ft of comfortable livi...
- 2 Beds
- 2 Baths
- B26088661 MLS
- 34986 Zip Code
- Kings Isle Phase 4 SubDv.

SHORT SALE! COME SEE THIS 3 BEDROOMS 2 BATHS 1 CAR GARAGE IN PORT ST LUCIE. LARGE BACKYARD. CERAMIC TILES THROUGHOUT THE HOUSE. THIRD PARTY APPROVAL REQUIRED. PROPERTY NE...
- 3 Beds
- 2 Baths
- B26031462 MLS
- 34983 Zip Code
- Port St Lucie Section 3 SubDv.

GATED COMMUNITY EAST OF US 1. BEAUTIFULLY MAINTAINED HOME IN MOVE IN CONDITION. This is a very spacious home over 1,600 sqft. YOU CAN WORK FROM HOME WITH 10X12 COMPUTER ...
- 2 Beds
- 2 Baths
- B26058134 MLS
- 34952 Zip Code
- Walton Court SubDv.

Welcome to 406 Poplar Avenue, a charming 2-bedroom, 1-bath CBS home in River Park offering comfort, character and plenty of possibilities. Features include a durable meta...
- 2 Beds
- 1 Baths
- B26074978 MLS
- 34952 Zip Code
- River Park Unit 2 SubDv.

This single-story pool home in River Park offers 2 bedrooms and 2 bathrooms in a strong CBS 1,261 square-foot layout. The open-concept design maximizes living space while...
- 2 Beds
- 2 Baths
- B26069792 MLS
- 34952 Zip Code
- River Park Unit 3 SubDv.

GORGEOUS is the best description of this home. This home has been totally remodeled, with Modern comforts and a stunning look right out of a magazine. Open, very spacio...
- 2 Beds
- 2 Baths
- B26088830 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- The Preserve At Savanna Club SubDv.

LAND OWNED! Water View 2 bed 2 bath is immaculate with an incredible back patio overlooking the water that is perfect for outdoor gatherings, fishing--or both! Quiet cul ...
- 2 Beds
- 2 Baths
- B26069087 MLS
- 34952 Zip Code
- Savanna Club Plat Iii SubDv.

Cash buyers ONLY! House needs considerable TLC. There is $22,000 in additional closing costs for a violation/lien that must be paid by the buyer at closing.
- 3 Beds
- 2 Baths
- A11911283 MLS
- 34983 Zip Code
- Port St Lucie Section 2 SubDv.

Experience comfort, style and unmatched value in the La Casita Floor Plan—featuring a spacious open-concept layout, 1 car garage, two bedrooms, two baths, a spacious walk...
- 2 Beds
- 2 Baths
- B26068270 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.

LAND OWNED This home has it all! Beautifully updated 2 bedroom, 2 bath home with 2020 metal roof, impact windows, plantation shutters, tile throughout, updated kitchen w/...
- 2 Beds
- 2 Baths
- B26080008 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- Savanna Club Plat Iii SubDv.

Welcome to your East Lake Village! Featuring a BRAND NEW AC unit installed October 2026! Entry level living room, kitchen, dining, and half bath downstairs along with ...
- 3 Beds
- 3 Baths
- B26091121 MLS
- 34952 Zip Code
- East Lake Village No 3 SubDv.

Discover true Florida living in the 2-bedroom, 2-bath Carlton model featuring a spacious layout, soaring vaulted ceilings, a covered front porch, and attached garage. Bui...
- 2 Beds
- 2 Baths
- B26060895 MLS
- 34952 Zip Code
- Spanish Lakes Riverfront SubDv.

None
- 2 Beds
- 2 Baths
- B26078697 MLS
- 34983 Zip Code
- Port St Lucie Section 25 SubDv.

Welcome to Kings Isle in St. Lucie West! This 2BR + den, 2BA CBS home offers 1,536 sq. ft. of comfortable living in a gated 55+ community in Port St. Lucie. Features incl...
- 2 Beds
- 2 Baths
- B26082341 MLS
- Kings Isle Bldg.
- 34986 Zip Code
- Kings Isle Phase Iia SubDv.

INVESTOR SPECIAL WITH GREAT POTENTIAL! Being Sold AS IS. Bring your vision and renovation ideas to this 2-bedroom, 2-bath Port St. Lucie home situated on a spacious lot i...
- 2 Beds
- 2 Baths
- B26090074 MLS
- 34983 Zip Code
- Port St Lucie Section 6 SubDv.

On SE Soneto Court in Port Saint Lucie, palms frame this single-story home and its attached carport. Tile flooring and chair-rail trim define the front living room, with ...
- 4 Beds
- 2 Baths
- A12112425 MLS
- 34983 Zip Code
- River Park Unit 7 SubDv.

Beautifully maintained 3BD/2BA home in the sought-after Savanna Club 55+ community. Offered fully furnished. Desirable split-bedroom floor plan with newer appliances, pla...
- 3 Beds
- 2 Baths
- B26042103 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- The Preserve At Savanna Club SubDv.

AUCTION. Affordable ranch home offers a great opportunity as a first home. Home features 3 beds, 2 baths, separate living and dining areas, an attached garage and the hom...
- 3 Beds
- 2 Baths
- B26030568 MLS
- 34953 Zip Code
- Port St Lucie Section 42 1st Replat SubDv.

Investor and contractor special. Short term financing is possible (only for qualified buyers and in first position only) with $125,000 down payment. This 3-bedroom, 2-bat...
- 3 Beds
- 2 Baths
- M20057103 MLS
- Handyman Investor Contractor Special Bldg.
- 34983 Zip Code
- Handyman Investor Contractor Special SubDv.

Discover true Florida living in the 2-bedroom, 2-bath Carlton model featuring a spacious layout, soaring vaulted ceilings, a covered front porch, and attached garage. Bui...
- 2 Beds
- 2 Baths
- R11167840 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.

NEW ROOF & A/C 2024. NEW ELEC PANEL - 9/25/2026. Great opportunity to own this Emerald II model w/oversized bedrooms & baths. Formal dining room & separate living room. ...
- 2 Beds
- 2 Baths
- B26066623 MLS
- Kings Isle - Isle Of Tuscany Bldg.
- 34986 Zip Code
- Kings Isle Phase Iia SubDv.

Investor, handyman and contractor special. Short term financing is possible (only for qualified buyers and in first position only) with $125,000 down payment. This 3-bedr...
- 3 Beds
- 2 Baths
- A12098503 MLS
- 34983 Zip Code
- Investor Contractor Specia SubDv.

Charming 3 bedroom, 2 bath home priced to sell and offering tremendous upside for first time buyers or investors. This solid property features a large eat in kitchen, a f...
- 3 Beds
- 2 Baths
- B26052294 MLS
- 34984 Zip Code
- Port St Lucie Section 18 SubDv.

Don't miss this incredible opportunity to own a well-maintained 3-bedroom, 2-bath CBS home in the heart of Port Saint Lucie! Whether you're a first-time homebuyer, downsi...
- 3 Beds
- 2 Baths
- B26059039 MLS
- 34953 Zip Code
- Port St Lucie Section 23 SubDv.

Beautiful 2 Bedroom, 2 Bath Home on a Quarter Acre in Port St. Lucie! ?Discover comfort, space, and Florida living in this well-kept 2 bedroom, 2 bathroom home situated o...
- 2 Beds
- 2 Baths
- M20053396 MLS
- Port St Lucie Sec 45 Bldg.
- 34983 Zip Code
- Port St Lucie Sec 45 SubDv.

NEW ROOF IN 2025! Discover the opportunity to enjoy Florida living in this conveniently located Port St. Lucie home! Situated in an established residential neighborhood, ...
- 2 Beds
- 2 Baths
- B26092892 MLS
- 34952 Zip Code
- Port St Lucie Section 40 SubDv.

Location! Location! Discover this Beautifully Updated Home in the heart of Port Saint Lucie! This 2 Bedroom (possible 3rd bedroom), 1-Bath, 1 Car Garage Home features a f...
- 2 Beds
- 1 Baths
- B26065808 MLS
- 34983 Zip Code
- Port St Lucie Section 3 SubDv.

Welcome home to this charming 2-bedroom, 1-bath starter home! Cute, cozy, and full of potential, this home is a great opportunity for first-time buyers, downsizers, or an...
- 2 Beds
- 1 Baths
- B26078992 MLS
- 34984 Zip Code
- Port St Lucie Section 13 SubDv.

Welcome to 415 NW Marsala Terrace in the desirable gated community of Kings Isle in St Lucie West! This spacious 2-bedroom, 2-bath home features a roof that is only about...
- 2 Beds
- 2 Baths
- B26081559 MLS
- Kings Isle Bldg.
- 34986 Zip Code
- Kings Isle Phase Iia SubDv.

Welcome to resort-style living in Savanna Club! This spacious 3BR/2BA lakefront home offers nearly 2,000 sq ft of living space, a 2-car garage, open split-bedroom floor p...
- 3 Beds
- 2 Baths
- B26085341 MLS
- Savanna Club Bldg.
- 34952 Zip Code
- Eagle's Retreat At Savanna Club Phase 2 SubDv.

Welcome to this charming 2-bedroom, 2-bath single-family home with tons of potential located in a quiet, non-HOA neighborhood in the heart of Port St. Lucie. Situated on ...
- 2 Beds
- 2 Baths
- R11161325 MLS
- 34983 Zip Code
- Port St Lucie Section 6 SubDv.

Enjoy comfortable Florida living with fewer exterior maintenance responsibilities in this well-maintained St. Lucie West villa. Offering 2 bedrooms, 2 bathrooms, and appr...
- 2 Beds
- 2 Baths
- B26056604 MLS
- Lakes At St Lucie West Bldg.
- 34986 Zip Code
- Lakes At St Lucie West Plat No 23 SubDv.

New tile roof 2025! Brand new water heater! Only 4 houses away from the resort-style pool, spa, fitness facility and clubhouse. Work out, jump in pool and be back home in...
- 2 Beds
- 2 Baths
- M20055656 MLS
- Tradition 18 Bldg.
- 34987 Zip Code
- Tradition 18 SubDv.

Move-in ready and filled with natural light, this bright and open Isle of Madeira home in Kings Isle offers 2 bedrooms, 2 baths plus a versatile den/office. The updated k...
- 2 Beds
- 2 Baths
- B26066844 MLS
- Isle Of Madeira Bldg.
- 34986 Zip Code
- Kings Isle At Isle Of Madeira SubDv.

PORT ST. LUCIE OPPORTUNITY PERFECT FOR INVESTORS, HANDYMAN, OR DOWNSIZING! Welcome to this charming 2-bedroom, 2-bath home offering an exciting opportunity to own in o...
- 2 Beds
- 2 Baths
- B26064794 MLS
- 34953 Zip Code
- Port St Lucie Section 19 SubDv.

This house has so much potential. Great location near Golf Course, close to beaches and shopping. Use your imagination to see what a beautiful home can be. Cash offers re...
- 3 Beds
- 2 Baths
- B26078508 MLS
- 34952 Zip Code
- South Port St Lucie Unit 5 SubDv.

Our newest Model: The Platinum offers incredible value with 2 full bedrooms plus a den, 2 baths, and a 1 car garage. Enjoy high vaulted ceilings, a chef's kitchen with a ...
- 2 Beds
- 2 Baths
- R11124110 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.
Our newest Model: The Platinum offers incredible value with 2 full bedrooms plus a den, 2 baths, and a 1 car garage. Enjoy high vaulted ceilings, a chef's kitchen with a ...
- 2 Beds
- 2 Baths
- R11124126 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.
Discover true Florida living in the 2-bedroom, 2-bath Carlton model featuring a spacious layout, soaring vaulted ceilings, a covered front porch, and attached garage. Bui...
- 2 Beds
- 2 Baths
- R11167867 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.

Our newest Model: The Platinum offers incredible value with 2 full bedrooms plus a den, 2 baths, and a 1 car garage. Enjoy high vaulted ceilings, a chef's kitchen with a ...
- 2 Beds
- 2 Baths
- B26010149 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.

Welcome to this beautifully maintained 2BR/2BA/2CG home in the desirable 55+ Cascades at St. Lucie West! Enjoy a spacious backyard with peaceful preserve views. The open ...
- 2 Beds
- 2 Baths
- B26055354 MLS
- Cascades Bldg.
- 34986 Zip Code
- Cascades SubDv.

**River Park CBS Home with Major Updates & Oversized Lot** Great opportunity in River Park! This CBS home features a **new roof**, **2023 air conditioning system**, and ...
- 3 Beds
- 2 Baths
- B26064664 MLS
- 34952 Zip Code
- River Park Unit 3 Tract E SubDv.
The Platinum offers incredible value with 2 full bedrooms plus a den, 2 baths, and a 1 car garage. Enjoy high vaulted ceilings, a chef's kitchen with a versatile peninsul...
- 2 Beds
- 2 Baths
- B26067892 MLS
- 34952 Zip Code
- Spanish Lakes One SubDv.
Homes for Sale in Port St. Lucie: How to Buy, Step by Step
The listings above are homes for sale across Port St. Lucie, updated automatically from the MLS. Above them is the part most search sites leave out: what actually happens between “I like this house” and getting the keys, in the order it happens in Florida.
I walk buyers through this process as their RE/MAX agent. For a zip-by-zip and price-by-price view of the city, use the main Port St. Lucie homes for sale page.
- Homes for Sale
- Pre-Approval
- Narrowing the Search
- Writing the Offer
- Inspection & Insurance
- Appraisal & Closing
- Related Searches
- FAQs
Step 1: Get Pre-Approved Before You Tour
A pre-approval is a lender's review of your income, assets and credit that says what you can borrow and under which program. In a competitive price range, sellers treat an offer without one as a maybe.
Do it first for a practical reason too: the loan program changes which houses work. An FHA or VA loan has minimum property standards, a condo may need project approval, and HOA dues count against your debt-to-income ratio. Knowing your program before you tour saves you from falling for a house your loan cannot close on. My mortgage page covers this in more depth.
Step 2: Narrow the Search
Port St. Lucie is big. The quickest way to narrow it is three decisions, in this order:
- HOA or no HOA. This splits the city roughly into the original platted neighborhoods and the planned communities.
- Which side of I-95. East means older homes, bigger lots and US-1; west means St. Lucie West, Tradition and newer construction.
- Price band. Each band captures a different kind of house — see $300K–$350K or $350K–$400K for examples.
Then I set up a listing alert so new homes reach you the day they hit the MLS.
Step 3: Write the Offer
Most Florida residential sales use a standard Florida Realtors/Florida Bar contract. The terms that matter most:
| Price and escrow deposit | The deposit shows you are serious and is held by a title company or broker. |
|---|---|
| Financing contingency | Sets how long you have to get loan approval, and what happens if you cannot. |
| Inspection period | A set number of days to inspect and decide. Under the common “as is” version you can cancel for any reason during this window. |
| Closing date | Usually driven by how long the loan needs; cash closes faster. |
| HOA / condo approval | Some associations must approve buyers before closing, which adds time. |
How strongly to write each term depends on how much competition the house has. I will tell you honestly when a lowball makes sense and when it will just lose you the house.
Step 4: Inspections and Insurance
This is the step that decides whether the house is really the one. In the inspection period I recommend:
- A full home inspection, plus a 4-point inspection on older homes (insurers often require it).
- A wind mitigation inspection, which can lower your premium.
- A pest (WDO) inspection, and septic and well checks where they apply.
- A real insurance quote on this specific house, while you can still walk away.
Roof age drives insurability in Florida. If the roof is near the end of its life, that becomes part of the negotiation, not a surprise after closing.
Ready to start with step one?
I can pre-approve you and set up your home search in the same conversation, so the houses you see are ones your loan will close on.
RE/MAX — Port St. Lucie agent.
Step 5: Appraisal, Final Approval and Closing
The lender orders an appraisal to confirm value. If it comes in low, you can renegotiate, bring more cash, or — depending on the contract — cancel. Meanwhile the title company searches title, checks for open permits and liens, and prepares the closing figures.
A few days before closing you will get a Closing Disclosure showing the final numbers. You do a final walk-through, sign, and fund. In Florida the title company or closing attorney usually handles the signing, and remote or mail-away closings are common for buyers still out of state.
Related Searches
- All Port St. Lucie Homes
- Mortgage & Pre-Approval
- Newly Listed Homes
- Homes $300K–$350K
- No-HOA Homes
- Relocating to Port St. Lucie
Frequently Asked Questions
How long does it take to buy a home in Port St. Lucie?
Once your offer is accepted, a financed purchase usually takes several weeks to close, driven mostly by the loan and any HOA approval. Cash purchases can close faster. The search itself depends on your budget and how competitive your price range is.
Do I need to be pre-approved before looking at homes?
It is strongly recommended. Sellers take pre-approved offers more seriously, and knowing your loan program early keeps you from pursuing homes that will not qualify.
What is the inspection period in a Florida contract?
It is a set number of days after acceptance during which you inspect the home. Under the common as-is contract you can cancel for any reason within that window and get your deposit back.
Who pays closing costs in Port St. Lucie?
Buyers and sellers each pay their own customary costs, and many items are negotiable. Your lender's Loan Estimate and the title company's figures will show your share.
Can I buy a home in Port St. Lucie without being there?
Yes. Many of my buyers tour by video and close remotely or by mail. I still recommend a local inspector and a careful review of insurance before you commit.
Does the buyer pay the agent?
Compensation is agreed in writing between you and your agent before touring, and sellers sometimes contribute. I explain the options up front so there are no surprises.
Homes for Sale in Port St. Lucie — the current listings appear at the top of this page and update automatically from the MLS.
Recently Sold: Port St. Lucie Homes
Closed sales of Port St. Lucie Homes, updated from the MLS. Want to know what your home would sell for today? Call (772) 359-1926.
Address Search
PORT ST LUCIE HOMES FOR SALE BY HOA COMMUNITY OR NEIGHBORHOOD
Listing Category
55+, Senior, Retirement Communities
Homes For SALE By Zip Code Port Saint Lucie
NEIGHBORHOODS
Interactive Map Search